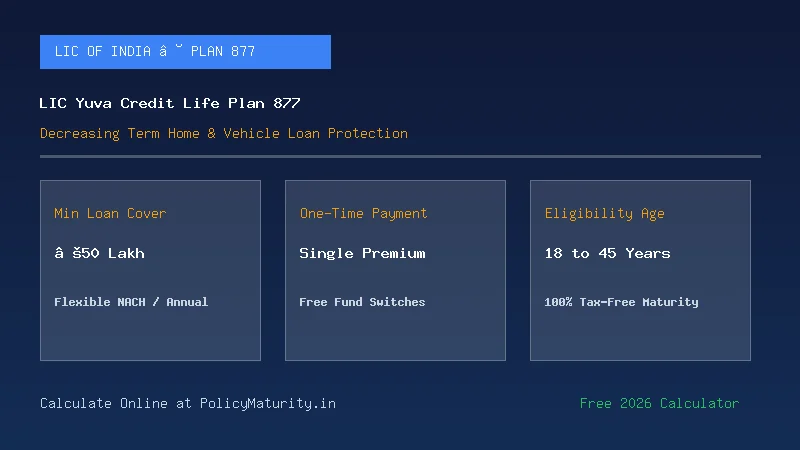
Yuva Credit Life is designed for a debt that is expected to become smaller over time, such as a home loan paid through regular instalments. The important point is that LIC promises the cover in its own schedule, so the insurance amount should not be treated as a live copy of the bank balance.
Match the contract to the loan details
The usual entry ages are eighteen to forty five and the standard starting basic cover is fifty lakh rupees, with acceptance subject to LIC's rules. Before choosing the term, compare the loan length and repayment plan with the insurance schedule, especially if the bank can change the interest rate later.
Why loan balance and cover can move apart
The cover reduces according to the selected contract terms even if your actual borrowing follows a different path after extra payments or missed instalments. The online alternative is Digi Credit Life; compare the schedule and application route as well as the premium, since the loan match matters most here.
Use the actual schedule for a claim estimate
For a simple example, take fifty lakh rupees starting cover and suppose the policy schedule shows eighty percent for the date being checked. That gives forty lakh rupees of scheduled cover, but eighty percent is only an example here; the actual year and amount must come from your own policy paper.
FAQ
Q: Will Yuva Credit Life pay my monthly EMI if I lose my job?
A: No. This is death protection under a reducing cover contract, not an unemployment or missed-EMI payment scheme. A change in income alone does not create that benefit.
Q: Does an early loan repayment automatically close Yuva Credit Life?
A: Do not assume automatic closure. Ask LIC about the policy options and check any lender assignment before cancelling cover or expecting an early-exit payment.
Q: Can Yuva Credit Life leave a gap after a loan rate rise?
A: Yes, the bank balance can differ from the contractual cover schedule. Review both figures when repayment terms change instead of assuming the loan is always fully covered.